Air ambulance bills, explained
There is no single Life Flight price.
A federal study of 2017 privately insured flights found median (middle) provider charges of $36,400 for a helicopter and $40,600 for a medical airplane. These are historical billed charges, not current prices or what you personally owe. Your share depends on your coverage and how the claim is processed.3
Your first bill may not be your final cost.
Compare the itemized bill with your explanation of benefits, the statement from your health plan showing what it covered and what you may owe. A pending or denied claim needs closer review.1
A 20-second explainer
How a Life Flight bill works
The essential distinction
One flight. Three different numbers.
A large charge can be frightening. It is a starting point for the claim, not a final answer about your responsibility. Keep the provider’s bill and your health plan’s explanation of benefits side by side.
Provider charge
What the air ambulance company billed for the flight.
Plan processing
What your insurer adjusted, allowed, paid, or denied.
Your share
What you may owe after the claim and applicable protections are reviewed.
Bill-reading guide
Read the bill in four parts
Look for these labels on the provider bill and your health plan statement. Wording differs by plan. The statement explains how your insurer handled the claim, so compare it with any bill requesting payment.1
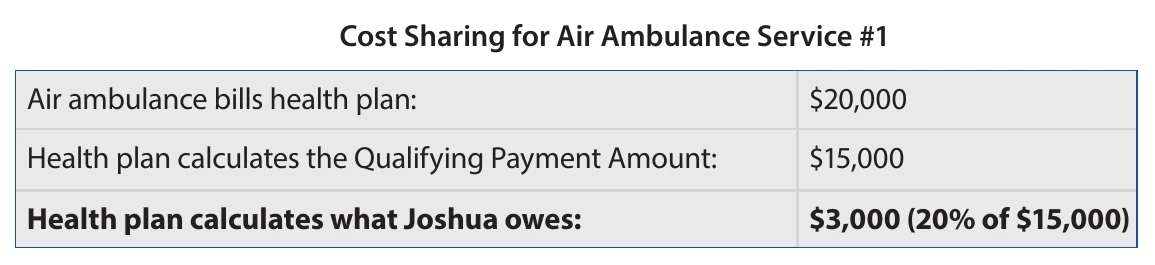
| What you see | What it means | What to check |
|---|---|---|
| Provider charge | The air ambulance company’s starting billed amount. It may include a transport charge and transported mileage. | Ask for an itemized bill. Confirm the flight date, aircraft, route, miles, and any separate charges. The charge alone does not establish what you owe. |
| Plan adjustment | Your health plan statement may show a negotiated or plan-determined amount and a reduction from the provider charge. | Do not treat the adjustment as an unpaid patient balance. Check how the claim was processed and whether the service was covered. |
| Insurer payment | The amount your plan paid or says it will pay the provider. | Is the payment final, pending, denied, or under appeal? A payment dispute between plan and provider is not automatically your bill. |
| Patient responsibility | The deductible (what you pay before some coverage begins), copay (a set fee), or coinsurance (a percentage) the plan says you owe, subject to applicable rules. | Compare this line on your health plan statement with the provider’s final bill. If they differ, ask both the plan and provider to explain before paying. |
If you have private insurance: for a covered flight by an air ambulance provider outside your plan’s network, federal law generally bars the provider from charging you the difference between its bill and your plan payment, and limits your share to the level you would pay for a provider in your plan’s network. It does not itself require coverage for a service your plan would not cover within its network.2
Cost, with context
Is there a typical Life Flight price?
No single amount predicts a California patient’s bill or final share. A provider’s charge may vary with the aircraft, type of transport, transported distance, and provider pricing. The plan’s coverage and applicable billing rules determine what happens next.
Air ambulance charges commonly include a base transport charge plus a charge for the miles the patient was transported.3
Coverage paths
Which coverage do you have?
Start with the program or plan that covered you on the flight date. Different rules apply.
Private insurance
Check your air ambulance benefit and health plan statement. For a covered flight, federal protections may limit what an out-of-network provider bills you. If the plan denied the claim, ask for the reason in writing and how to appeal.2
Original Medicare
Part B may cover an emergency air trip when rapid transport is needed and ground transport cannot provide it. For a covered trip, after the Part B deductible, you generally pay 20% of the Medicare-approved amount, not 20% of the full charge. Other coverage may change your share.4
Medi-Cal or another public program
Ask the program or managed-care plan how the flight was processed. Medicare, Medicaid, and TRICARE have their own coverage and billing protections; the private-plan No Surprises Act rules are not the right starting point.5
No insurance or self-pay
Request an itemized bill and ask about financial assistance or payment options. Do not assume an emergency flight came with a pre-service estimate. If you received one, keep it with the bill.6
A useful paper trail
What to gather before you dispute the bill
You can start even if you do not have every document. The federal Centers for Medicare & Medicaid Services recommends comparing bills, health plan statements, coverage details, correspondence, and medical records when assessing a surprise bill.1
- Provider’s itemized bill and any collection notices
- Every explanation of benefits from your health plan, including corrected versions
- Insurance card and coverage terms for the flight date
- Denial, appeal, or medical-necessity correspondence
- Transport record and relevant hospital records
- Call notes, dates, names, and proof of payments
What to do now
Three checks before paying
-
Match the records
Confirm the provider, date, service, and patient-responsibility amount agree across the bill and health plan statement. If not, ask the plan and provider to explain or correct them.1
-
Check your billing protection
For a covered flight under a private plan, ask how the No Surprises Act was applied. If the provider bills more than your permitted share, the federal Centers for Medicare & Medicaid Services has a help and complaint route.7
-
Keep the injury claim separate
If someone else’s negligence caused the accident, a lawyer can assess whether the flight expense belongs in an injury claim. That is a separate question from what your health plan must pay. No recovery is guaranteed.
When an accident caused the flight
How GJEL can help after an accident
A flight bill can involve three separate questions: what the provider charged, what your health plan covers, and whether the expense belongs in a claim against the person or business responsible for the accident. The goal is to find what you actually owe and which path may pay or reduce it. GJEL has described its experience reducing air ambulance bills for injured clients. Every bill and injury claim still needs its own review.
- Find the real balance. Compare the itemized bill, health plan statements, denial letters, and transport record so a provider charge is not mistaken for a final patient debt.
- Identify the next dispute. A denied health-plan claim may need an appeal and medical records. A bill above the permitted patient share may need a billing complaint. The route depends on the plan and the reason given.8
- Assess the injury claim. If another party caused a serious accident, GJEL can examine whether the flight and other treatment costs can be pursued as part of a personal injury claim and address outstanding medical bills during a case.
A free case review can clarify which of these issues GJEL can handle. It cannot guarantee that a health plan will approve a flight or that an injury claim will recover its full cost. Learn about how GJEL’s fees work.
Straight answers
Common questions about air ambulance bills
Does out-of-network mean I owe the difference?
Not automatically. For a covered flight under most private plans, federal law generally bars an air ambulance provider outside your plan’s network from charging you the difference between its bill and the plan payment. Check your health plan statement and plan type.2
What if my private health plan says the flight was not medically necessary?
Get the written denial and the plan language it cites. Ask the treating team for records explaining why rapid transport was needed. Follow the deadline and instructions on the notice for an internal appeal; ask whether an independent external review is available if the denial stands. A coverage denial and a bill above your permitted share are different disputes.8
Does Medicare pay the full bill?
For a covered flight under Original Medicare, the usual patient share is the Part B deductible plus 20% of the Medicare-approved amount, subject to other coverage and applicable exceptions.4